
Wealth exposure across jurisdictions
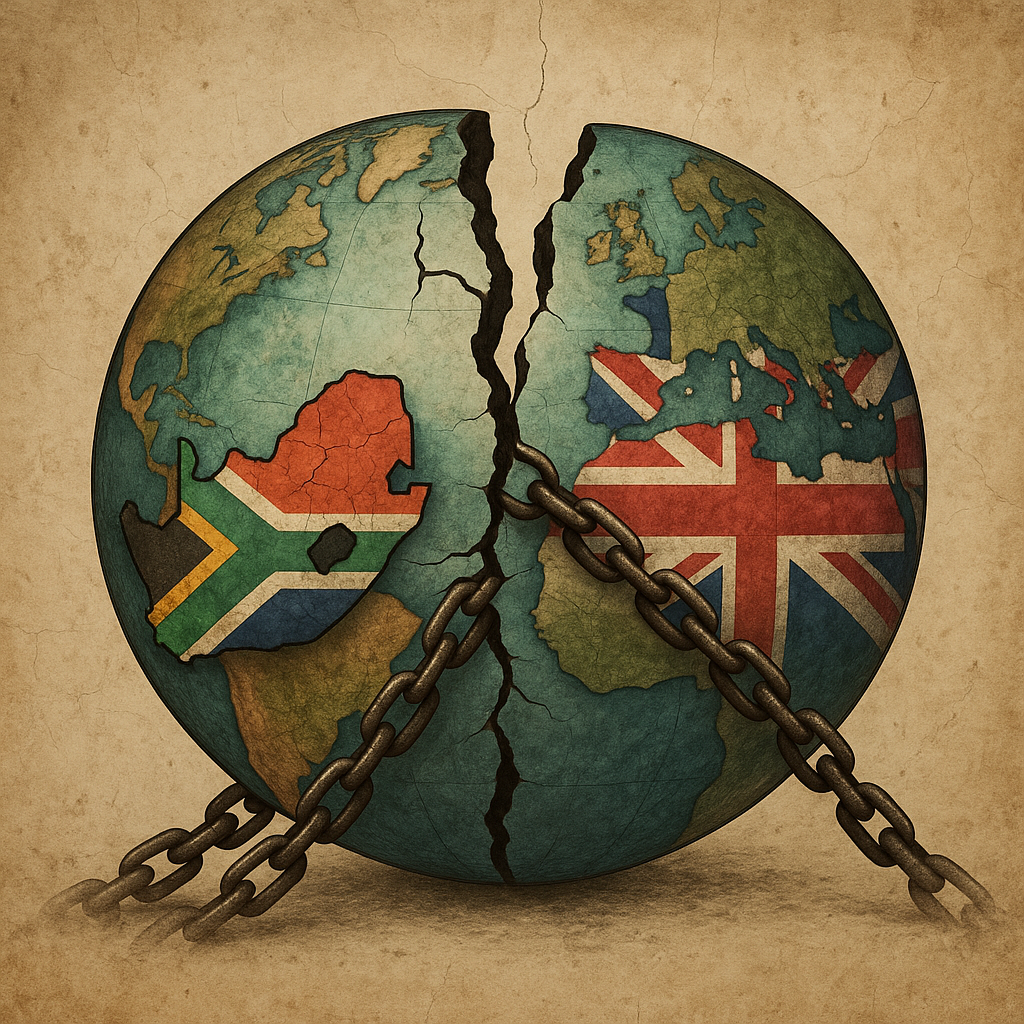
Cross-border divorce for SA-English families is complex. A SA divorce decree can be re-opened in London & vice-versa. This guide explains why.
Getting divorced when you live in both South Africa and the UK is tricky because a divorce in one country might not be final in the other. This means your money settlement could be changed years later if one country thinks it wasn't fair enough. Assets like trusts and even digital money can get tangled in different rules. To avoid big problems, it's best to plan for legal action in both countries from the start and get advice on how taxes will work in each place.
How do cross-border divorces between South Africa and the UK impact financial settlements?
Cross-border divorces between South Africa and the UK create a "two-key" dilemma. A divorce decree from one country may not be final in the other, allowing judgments to be reopened. English law, particularly Part III of the Matrimonial and Family Proceedings Act 1984, can "top up" overseas awards if the UK connection and original settlement are deemed inadequate, leading to further financial claims.
Get Cape Town news in your inbox
Stay updated with the latest stories from the Mother City.
The Mobility Trap – Why a Sandton Signature Rarely Locks the Door
London now hosts the biggest South-African diaspora on earth. The community stretches far beyond twenty-something teachers and two-year banking secondments; it includes Rand-billionaires who have re-domiciled JSE holding companies, private-equity partners who bounce between Constantia and Chelsea, and fourth-generation farmers whose teenagers board in Kent while the Drakensberg cattle station sits in a family trust. What none of these groups realise is that a Gauteng High Court decree - after however many millions have been carved up - can be unpicked in the Royal Courts of Justice under Part III of the Matrimonial and Family Proceedings Act 1984. The reverse is equally true: an English consent order can be reopened in Pretoria if it brushed aside a valid South-African antenuptial contract. Lawyers call it the “two-key” dilemma: turning one key in Johannesburg never dead-bolts the English lock.
The technical reason is simple. English law treats domicile and habitual residence as elastic concepts. A child born at St Mary’s Paddington, a retained one-bed in Mayfair, or merely keeping UK school fees up to date can anchor English jurisdiction years after the couple have flown home and toasted their “final” settlement with Klein Constante rosé. Once that anchor holds, the court simply asks whether the overseas provision is “adequate.” If the answer is no, a fresh claim can be launched, often a decade later.
The takeaway for any binational couple is blunt: plan for two sets of proceedings from the moment cracks appear. Early, simultaneous disclosure drafted to satisfy both Rule 43 affidavits and the English “full, frank and clear” standard is cheaper than a contempt sentence or Young-style satellite-tracking drama later. Treat the first decree as provisional, not conclusive.
Part III in Action – How London Retries a Sandton Split
Part III is not an appeal; it is a brand-new money suit. Six statutory filters decide whether England will “top up” an overseas award. Chief among them are the adequacy of the foreign payout and each spouse’s “connection” to the UK. Connection is proved by domicile (hard to shed), habitual residence (six months can suffice) or even a stated intention to return. Because English domicile clings like burrs, many South Africans discover - usually via a solicitor’s letter on expensively thick paper - that their R100 million Pretoria consent order is suddenly a floor, not a ceiling.
Once jurisdiction is established, the court can unpick almost everything. Maintenance can be increased, lump sums varied, and - crucially - UK pensions that were deliberately left untouched in the first round can be shared. “Add-back” jurisprudence means that assets spirited into Cape Town trusts or Gaborone shelf companies can be notionally returned to the pot, with costs threats used to flush out trustees. In one recent case a wife who had accepted a R40 million clean break in Pretoria walked away with an extra £6 million pension share after the husband’s London flat and City bonuses were re-examined.
Timing favours the claimant. There is no statutory deadline, only a vague requirement to act “promptly,” whereas South African forfeiture pleas must be raised within twelve months. The pragmatic response for the wealthier spouse is to pre-empt: launch first in South Africa, obtain a liquid-friendly order, then race to England for a mirror consent before the other side can file. Parallel proceedings sound wasteful, but they prevent the nastier surprise of a later unilateral strike.
Trusts, Shares and Crypto – Assets That Travel Faster Than Judgments
South Africans habitually park wealth in Mauritius, Guernsey or Channel-Island discretionary trusts to hedge the rand. English judges wield a blunt tool: if the settlement was created after the wedding and benefits spouse or children, they can vary it under s.24 Matrimonial Causes Act 1973, sometimes redirecting the entire fund. Trustees who plead “we are neutral” risk being joined as parties, forced to reveal letters of wishes, WhatsApp logs, even yacht itineraries. Conversely, a South African court may treat the same trust as “property” under s 7 of the Divorce Act, ordering a rand-value adjustment against the non-beneficiary spouse. One trust, two philosophies, months apart.
Private-company and mining interests face similar pincers. English precedent (H v H; Chai v Peng) treats unlisted shares as near-cash if a market can be engineered, empowering courts to mandate a sale, buy-back or receiver. South African benches prefer to leave operating entities intact, awarding cash instead. The sequence is therefore weaponised: sue first in London to engineer liquidity, and the company may hemorrhage value; sue first in Pretoria and the English top-up may still force a fire-sale later. Dual counsel can neutralise the threat by drafting simultaneous consent orders under the Reciprocal Enforcement of Judgments Act, each recognising the other’s carve-out.
Digital tokens add a fresh layer. English courts already treat crypto as property, traceable and freezable (AA v Persons Unknown). South Africa’s Cybercrimes Act 19 of 2021 lets judges demand private-key disclosure. A spouse who ticks “nil cryptocurrency” in a Pretoria affidavit may be ordered in London to type the 24-word seed phrase into the court recording system. Forward-thinking practitioners now append “crypto schedules” to early disclosure - public keys, exchange statements, staking contracts - to pre-empt Norwich Pharmacal applications against Binance, Luno or Valr.
Enforcing, Freezing and Tax-Harvesting – Turning Paper Relief into Hard Cash
London is the planet’s injunction capital. A without-notice freezing order can hit thirty banks in twenty jurisdictions within 24 hours under the “Babanaft” proviso. Once registered in South Africa under the Enforcement of Foreign Judgments Act, local banks face contempt if they allow a single rand to move. The mirror tactic works south-to-north: a South African s 31 attachment can be recognised in England under the common-law doctrine of obligation, pushing the debtor toward bankruptcy unless assets are repatriated. The practical playbook - freeze in London, register in Johannesburg - stops the classic flight of cash to SA private companies before the respondent can finish a cappuccino.
Tax mis-timing can devour more value than legal fees. Transferring a R50 million Constantia villa as part of a settlement attracts only 3 % South-African transfer duty, but if the recipient is UK-resident and later sells, capital-gains tax can sting at up to 28 %. Conversely, moving a Knightsbridge flat to a SA-domiciled spouse triggers 15 % stamp-duty land tax plus a 2 % non-resident surcharge unless the conveyance is choreographed during a temporary absence from the UK. Early dual-tax advice routinely saves 15-20 % of net asset value, dwarfing the cost of counsel.
Looking forward, practitioners lobby for a bespoke “Southern Accord” that would plug the treaty gap left by the Hague 1970 and 2019 instruments. Until ratification, the only safety net is coordinated common-law litigation, human-bridged by dual-qualified solicitors who speak both fiduciary dialects. For the internationally mobile entrepreneur, the emergency toolkit is clear: run a 183-day UK diary, segregate banking into sterling, rand and third-layer pots, refresh trust deeds every two years to strip nuptial flavour, pre-load shareholder shotgun clauses, and encrypt seed phrases under Shamir’s secret-sharing protocol. Treat every “final” order as a work-in-progress, because in the trans-Atlantic corridor between Table Mountain and the Thames, divorce decrees are rarely the last word - just the opening chapter of a longer, more expensive story.
[{"question": "
Why is a divorce settled in one country not always considered final in the other when dealing with South Africa and the UK?
\nDivorces involving both South Africa and the UK are complex due to differing legal principles. A divorce decree obtained in one country may not be fully recognized or considered final in the other. This creates a 'two-key' dilemma, meaning that even after a financial settlement is reached and a decree granted in one jurisdiction, the other country's courts (particularly the UK courts under Part III of the Matrimonial and Family Proceedings Act 1984) may have the power to re-evaluate and alter the financial arrangements if they deem the original settlement inadequate or if there's a strong connection to their jurisdiction. This can lead to significant financial upset years after the initial divorce.
\n","answer": ""},{"question": "What is the 'two-key' dilemma in cross-border divorces between South Africa and the UK?
\nThe 'two-key' dilemma refers to the situation where a divorce decree issued in one country (e.g., South Africa) does not automatically 'dead-bolt' or finalize the financial settlement in the other country (e.g., the UK). This means that a financial order, even if meticulously crafted and agreed upon in one jurisdiction, can be reopened and potentially altered by the courts of the other country. For instance, an English court using Part III of the Matrimonial and Family Proceedings Act 1984 can 'top up' an overseas award, or a South African court could reopen an English consent order if it disregarded a valid antenuptial contract, particularly when domicile or habitual residence concepts are considered elastic.
\n","answer": ""},{"question": "How can English law 'top up' an overseas divorce settlement, and what factors are considered?
\nEnglish law, primarily through Part III of the Matrimonial and Family Proceedings Act 1984, allows for a 'top-up' of overseas divorce settlements. This is not an appeal but a new financial claim. Six statutory filters determine whether England will intervene, with the adequacy of the foreign payout and each spouse's 'connection' to the UK being primary considerations. Connection can be established through domicile (which is difficult to shed), habitual residence (living there for as little as six months), or even a stated intention to return. If a UK connection is established and the foreign provision is deemed 'inadequate,' the English court can increase maintenance, vary lump sums, and even share UK pensions that were previously untouched. Assets held in trusts or shell companies can also be notionally returned to the marital pot.
\n","answer": ""},{"question": "What challenges do international trusts, shares, and digital assets pose in cross-border divorces?
\nInternational assets like trusts, private company shares, and cryptocurrencies add significant complexity. English judges can vary trusts established after marriage for the benefit of a spouse or children under s.24 Matrimonial Causes Act 1973, potentially redirecting the entire fund. South African courts might treat the same trust as 'property' under s 7 of the Divorce Act, leading to different valuations and outcomes. For private company shares, English precedent may treat them as near-cash, mandating sales, while South African courts prefer to keep operating entities intact. Digital tokens are recognized as property in both jurisdictions, making them traceable and subject to freezing orders, and spouses may be compelled to disclose private keys. These differing approaches necessitate careful, dual-jurisdictional planning to avoid asset dissipation or unforeseen tax liabilities.
\n","answer": ""},{"question": "What are the critical tax implications to consider in SA-UK cross-border financial settlements?
\nTax mis-timing can significantly erode the value of financial settlements. For example, transferring a R50 million property in South Africa might only incur a 3% transfer duty, but if the recipient is UK-resident and later sells it, they could face up to 28% capital gains tax. Conversely, transferring a UK property to a South African-domiciled spouse might trigger 15% stamp duty land tax plus a 2% non-resident surcharge, unless the conveyance is strategically timed. Early, dual-tax advice is crucial and can save 15-20% of the net asset value, often dwarfing legal fees. Understanding the tax implications in both jurisdictions for property, investments, and other assets is vital to prevent unintended financial losses.
\n","answer": ""},{"question": "What proactive steps should binational couples take to mitigate risks in a cross-border divorce?
\nFor binational couples with ties to both South Africa and the UK, the most critical step is to plan for legal action in both countries from the outset, even at the first sign of marital difficulty. This includes early, simultaneous financial disclosure drafted to satisfy the requirements of both jurisdictions. It's advisable to treat the first divorce decree as provisional rather than conclusive. Seeking dual-qualified legal and tax advice from the beginning is paramount. Strategies may include launching parallel proceedings to pre-empt unilateral actions by the other spouse, carefully structuring asset holdings (e.g., segregating banking), refreshing trust deeds to clarify their nature, and pre-loading shareholder agreements. The goal is to coordinate litigation and financial planning to prevent assets from being unpicked or subjected to unexpected claims years down the line.
\n","answer": ""}]
Liam Fortuin is a Cape Town journalist whose reporting on the city’s evolving food culture—from township kitchens to wine-land farms—captures the flavours and stories of South Africa’s many kitchens. Raised in Bo-Kaap, he still starts Saturday mornings hunting koesisters at family stalls on Wale Street, a ritual that feeds both his palate and his notebook.
View all articles →