
Cape Town retailer Pepkor eyes digital banking leap
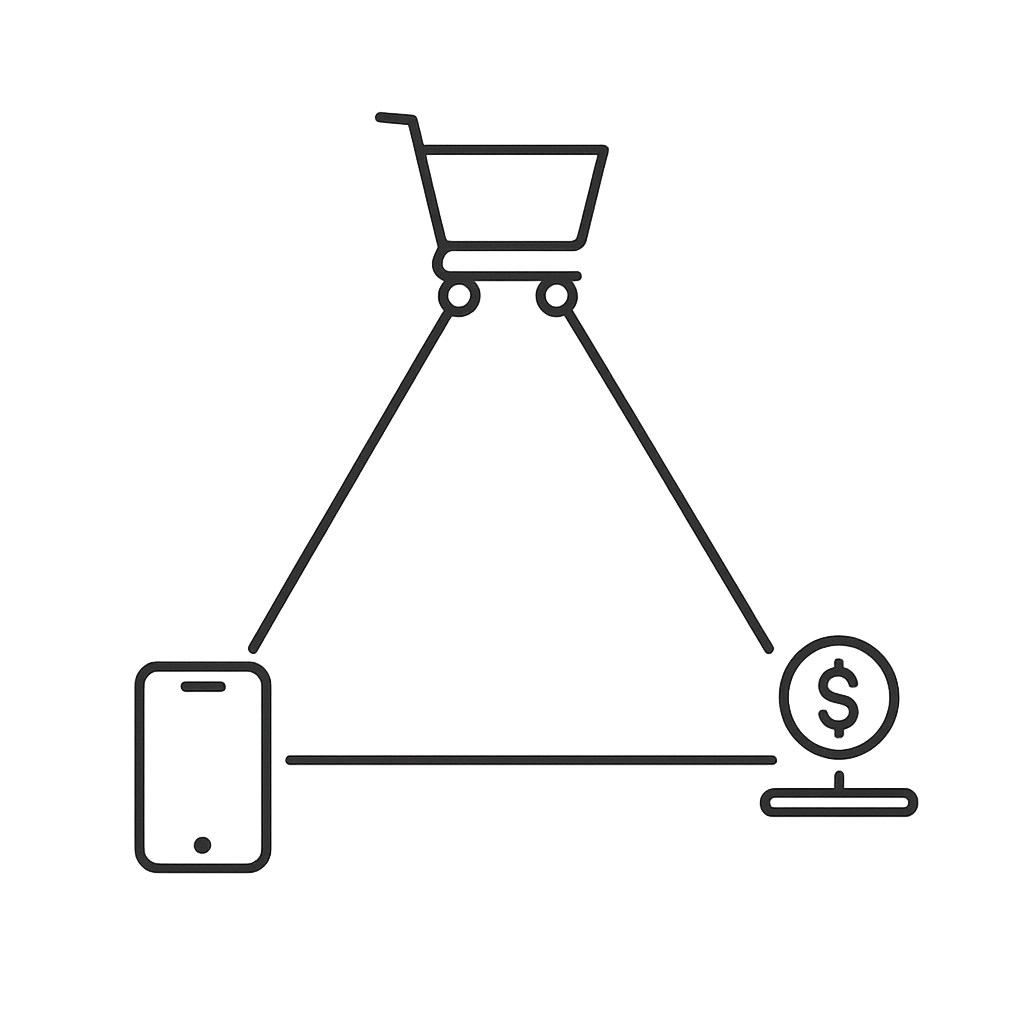
Pepkor is re-engineering South Africa's financial landscape by launching a digital bank, leveraging its retail footprint to serve underserved communities.
Pepkor, a big retail company, wants to become a bank in South Africa. They'll use their many stores, like Pep and Ackermans, as 'branches' to offer banking services. This includes free accounts and small loans, helping people who don't usually use banks. They plan to make this happen by early 2025.
What is Pepkor's strategy to become a bank in South Africa?
Pepkor plans to leverage its extensive retail store network (2,519 locations) to offer banking services. By converting existing stores into "branches" and utilizing Flash agents, they aim to provide no-monthly-fee accounts, nano-loans, and smartphone bundles, targeting the unbanked and underbanked population by "following the rand" where their customers already shop and spend.
Get Cape Town news in your inbox
Stay updated with the latest stories from the Mother City.
1. From Sock Rails to Savings Accounts – The 2,519-Store Branch Network Nobody Saw Coming
Late on a weekday, the Foreshore precinct ticks to the familiar beat of reversing trucks and traffic-light hawkers. Up on the eleventh floor of Pepkor’s headquarters, however, the clocks seem to run slower. A glass-walled space called “Project Riverbank” is litterless, the air heavy with the soft squeak of whiteboard markers. Merwe Scholtz, head of new ventures, sketches a plain triangle: corner one reads “store visits,” corner two “phone access,” corner three “deposit power.” He tells the mixed crowd - actuaries in sneakers, Flash agents in reflective jackets - that this three-sided doodle is the blueprint for the country’s next deposit-taking institution.
The session is the latest waypoint in a journey that began with dog-eared lay-by ledgers and is scheduled to climax, regulatory gods willing, in Q2 2025 when a licensed digital bank goes live. There will be no brass plates, no two-hour queues, and no free coffee. The “branch” will be the plastic table you already pass while hunting for school socks in 2,519 Pep, Ackermans, Tekkie Town or Flash shops. Same cashier who sells you airtime will soon swipe your first R50 into a no-monthly-fee account.
Executives call the philosophy “following the rand.” Translation: watch where a wage is spent on a Saturday and you will know which financial tools actually matter to that shopper. Every year the group vacuums up eleven billion transactions from tills, money-transfer switches and USSD sessions. The numbers light up a map of the excluded: 6.3 million adults who store value almost entirely inside retail corridors. Owning that footfall, says deputy CFO Rina Makhubu, lops the priciest part off a normal bank build. “We’ve been acquiring customers for thirty years - one pair of shoes at a time.”
2. How a Clothing Giant Buys Its Way into Prudential Heaven
South Africa’s “twin-peak” rules keep bank supervision separate from market conduct, letting retailers flirt with credit without meeting full prudential tests. Pepkor’s 2023 takeover of JG Fintech - the parent of Flash - handed it a registered credit book and remittance rights, but taking insured retail deposits still required the real trophy: a banking licence. After an 1,100-page dossier and weeks of stress-tests in Johannesburg and Durban data bunkers, the Prudential Authority stamped “in-principle approved” in October 2023. Flash agents had to prove algorithms could separate granny’s grocery money from a pyramid scheme’s wash trades.
To sweeten the deal, the proposed bank was locked inside a non-operating holding company, copying the ring-fence Discovery Bank used in 2018. An independent risk board, chaired by former Investec London boss Richard Wainwright, meets monthly beneath black-and-white photos of the first Pep store in Upington - corporate memory that apartheid-era shelves and today’s APIs are chapters of the same story.
While regulators pored over servers, engineers in Stellenbosch were busy shrinking banking code into 30-byte USSD strings. Over seventy percent of the target market still carries feature phones, so the primary app is the same text menu that birthed M-Pesa. The proprietary “String-30” protocol knocks roughly twelve cents off each session; in a month of daily use that equals a loaf of brown bread. Behind the humble menus sits a cloud-native core on AWS with failover at state-owned Teraco, ensuring exchange-control data never leaves local soil. APIs are wide open, letting rival shops white-label the wallet if they feed reciprocal volume - talks are already advancing with two rural grocery chains that crave “the Flash bank” posters their customers keep asking about.
3. Nano-Loans, R35-a-Week Phones and the New Math of Township Credit
Pepkor’s lending DNA dates to 2008 when the purchase of Ackermans dragged a furniture book full of stoves and sofas onto the balance sheet. Field teams learned to unhook a Defy fridge while calming a family row - tough schooling that also produced fifteen years of repayment behaviour. Analysts found the strongest predictor of default was not salary slips but whether a buyer had ever exchanged kids’ shoes for the wrong size. The counter-intuitive signal matters because it captures relational diligence; people who bother to queue at Customer Service tend to honour debt as well.
The new bank will convert that insight into advances from R50 to R500, repayable in seven days for a flat five percent fee. Annualised, the number looks ugly; compared with a mashonisa who charges thirty percent a week, it is liberation. Each on-time repayment feeds a psychometric graph that unlocks larger loans - a staircase product head Scholtz calls “trust compounding.”
Device scarcity is the next domino. National smartphone ownership tops 86%, yet among Pepkor shoppers it drops to 47%. The solution: bundle a Vodacom-approved 4G handset that wholesales at R899 but walks out at R49 down plus R35 a week for twenty-six weeks. The debit hits the new wallet the same day wages arrive. Because the bank controls the SIM, airtime buys become a proxy payslip - anyone topping up R5 at 19:15 after purchasing electricity is broadcasting cash-flow rhythm. Vodacom gains a data user without handset risk; Pepkor gains a banking client whose phone doubles as a QR-code checkout tool in store.
4. Kiosks, Grants and the Race for Four Million Wallets
The physical face of the bank is a canary-yellow cube the size of an old ATM: fingerprint reader, thermal printer, 4G router, designed by engineers who once built Pick n Pay self-checkouts and now tuned for township dust and spilled Coke. One pilot outlet in Motherwell logged 1,800 deposit touches in four weeks, 40% after tills had closed. Security piggybacks on existing cash-in-transit runs; guards simply swap sealed cassettes from the kiosk into the same armoured crates that already collect store takings - a detail regulators adored because zero new cash vans hit the road.
Revenue will not rely on classic net interest margin alone, targeting just 45% from that source. The rest is slated to flow from: 0.8% interchange on QR purchases (half the card schemes), a 20% cut of insurance policies underwritten by Sanlam, sale of FMCG analytics to suppliers, FX margin on Flash’s R2-billion annual corridor into Zimbabwe and Mozambique, and handset origination fees. Absa CIB reckons ancillary income could surpass R3 billion if four million wallets are active by 2028 - an umbrella against the apparel margin squeeze that has gnawed the group since 2019.
Competitors are already twitching. Capitec scoffed publicly at “a retailer with a wallet” yet quietly trademarked “Capitec Business in a Box,” a POS bundle for spaza owners. TymeBank slashed its 4G phone price to R1 in MTN outlets. Even Postbank floated a tender for 5,000 “retail partnership points,” vocabulary lifted straight from Pepkor’s kiosk pitch. Globally, Mexico’s Oxxo network and India’s Reliance Jio are reference points, but South Africa’s store density - one Pepkor outlet per 2,050 low-income adults - hints that similar network effects are mathematically within reach.
Training shelf packers to sell regulated products is the final mile. A “Tier 2” representative certificate demands 120 study hours, so Pepkor teamed with Boston City Campus to shrink coursework into tablet lessons agents can swipe offline. Graduates earn a 10% salary kicker and a lime-green lanyard that authorises kiosk duty. Pass rates hover at 72%, well above industry median, perhaps because graduates already speak “stokvel” and “gogo” with their customers. As the Mdantsane store manager - once a schoolteacher - puts it: “My best cashier was already a banker; the law just hadn’t noticed.”
Grants, spoofing and reputational ghosts still cast shadows. More than a third of pilot users draw SASSA payments, exposing the model to any policy swing that diverts welfare through state pipes. A single USSD spoof could drain wallets capped at R15,000 - life savings for some. And township gossip still confuses the new wallet with an old furniture book famed for repossessing beds. Inside Project Riverbank, Scholtz has added a fourth whiteboard vertex: “Customer stories.” Engineers open each stand-up by reading pilot quotes. One, in red marker, says: “The shop that sells my child’s uniform can now keep her school fees safe.” Whether that feeling can scale to four million hearts will decide if South Africa’s quiet retail experiment becomes its most lasting financial revolution.
[{"question": "What is Pepkor's strategy to become a bank in South Africa?", "answer": "Pepkor plans to leverage its extensive retail store network (2,519 locations) to offer banking services. By converting existing stores into \"branches\" and utilizing Flash agents, they aim to provide no-monthly-fee accounts, nano-loans, and smartphone bundles, targeting the unbanked and underbanked population by \"following the rand\" where their customers already shop and spend. They received in-principle approval for a banking license in October 2023 and aim to go live by Q2 2025."}, {"question": "How will Pepkor's retail stores function as bank branches?", "answer": "Pepkor's existing stores, including Pep, Ackermans, Tekkie Town, and Flash shops, will serve as \"branches.\" Customers will be able to perform banking transactions, such as opening no-monthly-fee accounts and making deposits, at the same cashiers who sell them other retail items. The physical interface will often be a canary-yellow kiosk equipped with a fingerprint reader and thermal printer, designed for high-traffic, low-cost operations within the stores."}, {"question": "What financial products will Pepkor Bank offer?", "answer": "Pepkor Bank will offer no-monthly-fee accounts for deposits, nano-loans ranging from R50 to R500 repayable in seven days for a 5% flat fee, and bundled smartphone deals (e.g., a 4G handset for R49 down plus R35 a week). They also plan to offer services like insurance policies underwritten by Sanlam and potentially white-label wallet services for other rural grocery chains."}, {"question": "How is Pepkor addressing the digital divide and ensuring accessibility for its target market?", "answer": "Recognizing that over 70% of their target market still uses feature phones, Pepkor has developed a primary banking application based on USSD (Unstructured Supplementary Service Data) strings. This \"String-30\" protocol significantly reduces transaction costs. They also offer bundled smartphone deals to increase digital access, and the bank controls the SIM, allowing airtime purchases to act as a proxy for income in credit assessments."}, {"question": "What is Pepkor's approach to lending and credit assessment?", "answer": "Pepkor's lending strategy draws on 15 years of repayment behavior data from its retail credit book. They've found that customer diligence, like exchanging shoes for the correct size, is a strong predictor of repayment. Their nano-loans are designed as a \"staircase product,\" where on-time repayments build a psychometric graph that unlocks larger loans, fostering \"trust compounding.\" This aims to be a more accessible alternative to informal lenders."}, {"question": "What is the revenue model for Pepkor Bank beyond traditional interest margins?", "answer": "Pepkor Bank anticipates only 45% of its revenue from classic net interest margin. The remaining income is expected from 0.8% interchange on QR purchases, a 20% cut of insurance policies underwritten by Sanlam, sales of FMCG analytics to suppliers, FX margin from Flash's cross-border remittance services (into Zimbabwe and Mozambique), and handset origination fees. They project ancillary income could exceed R3 billion if four million wallets are active by 2028."}]
Tumi Makgale is a Cape Town-based journalist whose crisp reportage on the city’s booming green-tech scene is regularly featured in the Mail & Guardian and Daily Maverick. Born and raised in Gugulethu, she still spends Saturdays bargaining for snoek at the harbour with her gogo, a ritual that keeps her rooted in the rhythms of the Cape while she tracks the continent’s next clean-energy breakthroughs.
View all articles →