
Credit use in SA: Why borrowing has become a lifeline for millions
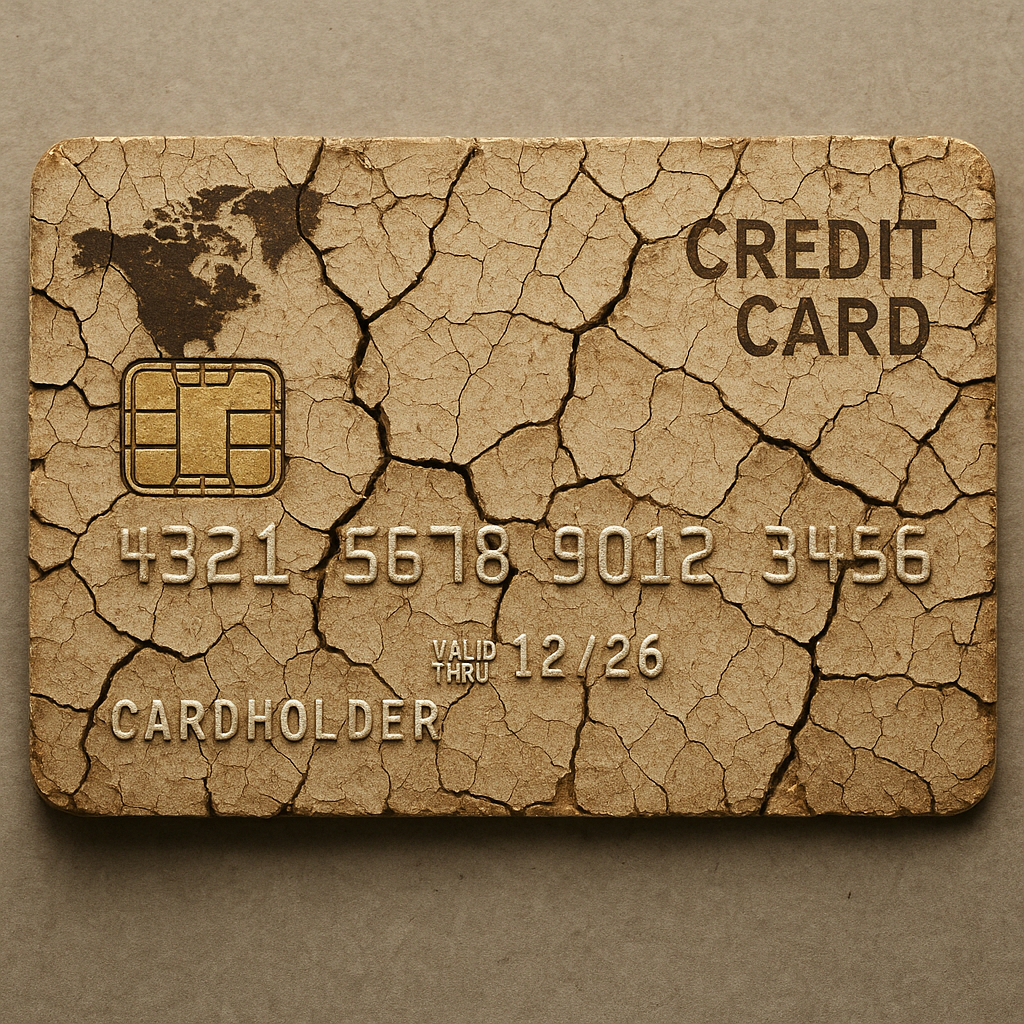
Many South African households rely on debt to survive monthly, facing high interest rates and informal lenders due to unstable incomes.
In South Africa, many people rely on "survival credit" to buy everyday things like food and transport, borrowing money quickly between paychecks. This often means very high interest rates. Some use special shopping club schemes where they pay off groceries over many months, while others turn to informal lenders who charge huge fees. This cycle traps many in debt, making it hard to escape, even with new ways to lend money safely emerging.
What is "survival credit" in South Africa?
"Survival credit" in South Africa refers to the widespread practice of households relying on short-term borrowing, often with high interest rates, to cover essential living expenses between salary payments. This phenomenon, which includes using budget clubs for groceries and informal loans, has become the primary means for many to bridge financial gaps for necessities like food, transport, and utilities.
Get Cape Town news in your inbox
Stay updated with the latest stories from the Mother City.
1. Mall Rush at 09:00 – When Groceries Are Bought with Tomorrow’s Money
Every 25th of the month, suburban shopping centres fill before breakfast. Families circle the parking lot, racing to be first inside the supermarket where the butcher, the phone kiosk and even the pharmacy now run “budget clubs.” These schemes let you fill a trolley with maize, oil, nappies and paraffin today, then drip-feed the bill over twelve, twenty-four or thirty-six months. The average basket costs about R1 200 in cash, yet the swipe-and-sign shopper is charged an extra 21 % to cover the credit sweetener. The receipt still gets signed, because heading home with half the list untouched feels worse than the invisible surcharge.
Payments Association logs show this scene plays out roughly 15 million times a month, proof that borrowing is no longer a clever planning tool - it is the oxygen households inhale between salaries. Wonga’s 2023 national survey labels the phenomenon “survival credit,” a label that sounds dramatic until you watch the queues.
Credit, in other words, has become the bridge stretched over the chasm that opens the moment last month’s wage evaporates on school transport, burial-society levies and lights that stay on for only 20 prepaid units at a time.
2. The Balance-Sheet Reality: 73 % Swim, 27 % Sink Slowly
Researchers spoke face-to-face with 12 086 adults, slicing the sample by province, income bracket and postal code. The middle-of-the-road participant earns R7 800, supports 4.3 people and is listed on 3.7 legal contracts plus 1.2 handshake deals. Barely more than a quarter can lay hands on cash equal to one full salary without ringing someone else.
Dig into the numbers and you meet two camps:
- The saver minority - usually civil servants whose unions negotiate funeral cover and pension deductions, and who stash spare rands on a retailer gift card.
- The liquidity majority - security guards, street barbers, grant caregivers and the under-employed who borrow for five-to-ten days every single month.
Forty-three percent of the second group say their latest loan was smaller than R2 500 and triggered by a so-called micro-crisis: a burst geyser, a midnight taxi to hospital, school shoes left behind on a bus. In a textbook universe those surprises are what petty cash is for; in the lived one they are the gateway to another repayment plan.
3. WhatsApp Loans and Funeral Shaming – Life with the Mashonisas
One in seven respondents admitted visiting an unregistered lender within six months. Ethnographers followed 120 such clients across KwaZulu-Natal and Gauteng and logged a shadow market that runs on voice notes, school-gate handovers and backyard stokvels. A typical deal dishes out R500–R3 000 for 30 days, collects 30–50 % flat interest each week and is secured by an ATM or SASSA card plus the associated PIN.
Fall behind and the penalty is “double-up” next week or a visit from a runner who knows your cousins. Because no data is shared with the bureaus, a borrower can hop between five or six mashonisas before anyone notices the holes. The final collector, however, arrives at a funeral, a stokvel draw or your place of work - social enforcement beats any courtroom.
4. Locked Out of the Formal Gate – Why Algorithms Say “Too Risky”
The National Credit Act insists that licensed banks leave a customer with 30 % of net pay “free” after all deductions. The rule was tightened after the 2008–2010 unsecured bubble burst, and it now disqualifies millions whose wage slips wobble.
About 45 % of economically active adults earn something in the informal pool - piece jobs, rent from a backyard room, rand-plus-pula remittances. Bank statements show erratic drops: R1 800 here, R400 there, then a R6 000 gift from London. To an algorithm that pattern reads “chaos,” so the application dies. Even a spotless credit record can’t save a security guard who nets R5 500 but already surrenders R1 800 to two furniture stores and R1 200 to a clothing account. Left with R2 500, he is officially “over-indebted,” a label that shoves him back into the arms of the very mashonisas the law hoped to crush.
5. Plastic, Phones and Payroll – Glimmers of a Safer Path
Hope is sprouting in unlikely places. Inside Sibanye-Stillwater’s hostels and Servest’s office parks, workers can divert as little as R50 the instant wages land. Once R1 000 accumulates, the same app green-lights an emergency advance at 1 % a month, deducted painlessly from payroll. Early numbers show garnishee orders down 38 % and mashonisa visits down 12 %.
Over in cyberspace, open-banking pilots led by TymeBank and Jumo mine airtime-buying habits and 03:00 wallet balances to price “thin-file” customers. Default rates sit below 4 %, half the traditional unsecured average, but POPIA red tape still slows roll-out.
Even Parliament is awake: a draft amendment would cap any loan tied to a SASSA grant at repo plus 10 %, effectively banning the 05:00 queues that currently stretch outside Finbond branches. Whether these shoots can grow fast enough to outpace the next rate hike - an event the NCR warns will tip 600 000 people back into default - is the wager that will decide if the plastic edge becomes a bridge or a cliff.
[{"question": "What is 'survival credit' in South Africa?", "answer": "Survival credit refers to the practice of individuals and households in South Africa relying on short-term, often high-interest, borrowing to cover essential daily expenses between paychecks. This includes using budget clubs for groceries, informal loans from 'mashonisas', and other quick credit schemes to bridge financial gaps for necessities like food, transport, and utilities."}, {"question": "How do 'budget clubs' for groceries work, and what are their implications?", "answer": "Budget clubs, found in supermarkets and other retail outlets, allow individuals to purchase groceries and other essential items (like maize, oil, nappies, paraffin) immediately. They then pay off the bill over an extended period, typically 12, 24, or 36 months. While convenient, these schemes often come with a significant 'credit sweetener,' adding an average of 21% to the cash price of the goods, trapping consumers in long-term debt for everyday necessities."}, {"question": "What is the financial reality for most South Africans regarding their ability to handle emergencies?", "answer": "The data indicates that barely more than a quarter of South Africans can access an amount equivalent to one full salary in cash without borrowing. The majority (the 'liquidity majority'), including security guards, street barbers, and grant caregivers, borrow for short periods (5-10 days) every month. For 43% of this group, loans smaller than R2,500 are triggered by 'micro-crises' like a burst geyser or medical emergencies, which quickly lead to new repayment plans."}, {"question": "Who are 'mashonisas,' and what are the risks associated with their loans?", "answer": "Mashonisas are informal, unregistered lenders in South Africa. They typically offer loans ranging from R500 to R3,000 for 30 days, charging extremely high-interest rates of 30-50% flat interest each week. These loans are often secured by an ATM or SASSA card along with its PIN. Falling behind on payments can lead to 'double-up' penalties or visits from enforcers, and due to no data sharing with credit bureaus, borrowers can get trapped in a cycle with multiple mashonisas, facing social enforcement rather than legal action."}, {"question": "Why are many South Africans 'locked out' of formal credit?", "answer": "The National Credit Act requires licensed banks to ensure a customer has 30% of their net pay 'free' after all deductions, which disqualifies millions whose wage slips are unstable. Additionally, about 45% of economically active adults earn uneven income from the informal economy, which algorithms interpret as 'chaos,' leading to rejected applications. Even those with a spotless credit record can be deemed 'over-indebted' if their existing commitments leave them with too little disposable income, pushing them towards informal lenders."}, {"question": "What new initiatives are emerging to offer safer credit options?", "answer": "Hope is emerging through several initiatives. Some employers, like Sibanye-Stillwater and Servest, allow workers to save small amounts directly from their wages, then offer emergency advances at 1% interest per month, significantly reducing garnishee orders and mashonisa reliance. Open-banking pilots by TymeBank and Jumo are using data from airtime-buying habits and wallet balances to assess 'thin-file' customers, achieving default rates below 4%. Furthermore, a proposed amendment to the law aims to cap loans tied to SASSA grants, offering more protection to vulnerable individuals."}]
Sizwe Dlamini is a Cape Town-based journalist who chronicles the city’s evolving food scene, from boeka picnics in the Bo-Kaap to seafood braais in Khayelitsha. Raised on the slopes of Table Mountain, he still starts every morning with a walk to the kramat in Constantia before heading out to discover whose grandmother is dishing up the best smoorsnoek that day.
View all articles →